

Building a high-value business takes years of relentless execution, yet founders can give up a meaningful share of their proceeds in the sale process itself. Focusing entirely on maximizing gross enterprise value while ignoring personal wealth structuring can cost founders substantially in avoidable taxes, poor liquidity timing, and misaligned deal structures.
A successful liquidity event requires coordinating M&A strategy with personal wealth planning well before signing a Letter of Intent (LOI). This exit roadmap covers how to coordinate your transaction advisory with personal estate planning to help protect your wealth before, during, and after a sale.
1. The Pre-Sale Gap: Aligning Enterprise Value with Personal Financial Needs
Most founders start the M&A process by asking what their business is worth on the open market. The far more critical question is understanding the exact net liquid proceeds required to support their personal goals after the exit.
- Calculating Your Net Proceeds Target: Work with a wealth manager to establish your post-sale capital requirement. Factor in inflation, future legacy goals, and lifestyle expenditure to work backward toward your target enterprise purchase price.
- Closing the Structural Gap: If market valuation falls short of your post-tax wealth requirement, adjusting your exit timeline by 12 to 24 months may give you time to improve revenue quality rather than accept a discounted sale, although market conditions and valuations can also move against you.
- Differentiating Paper Value from Cash Proceeds: M&A purchase prices often include rolled equity, earn-outs, and escrow holdbacks that carry significant risk and delay actual cash realization.
2. Pre-LOI Tax Structuring: Protecting Your Proceeds Before Signing
Once an LOI is signed, your tax minimization options narrow considerably. Preparing your personal estate and corporate structure prior to entering exclusivity is important for managing capital gains tax.
- Grantor Retained Annuity Trusts (GRATs) & SLATs: Transferring non-voting equity to a GRAT or a spousal lifetime access trust (SLAT) before value rises can shift future appreciation to beneficiaries with little or no gift tax, through the GRAT annuity structure or the lifetime gift exemption ($15 million per person in 2026). Timing matters: transfers need a qualified appraisal, and once a sale is effectively agreed the IRS can tax the gain to the founder anyway under the assignment-of-income doctrine. A GRAT also fails if the grantor dies during its term.
- Qualified Small Business Stock (QSBS / Section 1202): For shares in a qualifying C corporation, Section 1202 can exclude federal tax on gain up to the greater of $10 million or 10 times basis for stock issued on or before 4 July 2025 and held more than five years. For stock issued after that date the cap is $15 million (or 10 times basis), with a 50% exclusion after three years and 75% after four. Eligibility is set when the shares are originally issued and cannot be created on the eve of a sale: the company must run a qualified active business (many service businesses, including consulting, financial services, law and health, are excluded) and meet a gross-assets limit. Gifting shares to family members or certain trusts may multiply the cap, and some states, including California, do not follow the federal exclusion.
- State Residency and Holding Vehicles: Changing domicile or using certain non-grantor trusts before a liquidity event may reduce state income tax on a large gain. High-tax states audit residency changes closely, the move has to be genuine and well documented, and New York and California tax incomplete-gift non-grantor (ING) trusts as if the founder still owned the assets.
Key Takeaway: Tax strategy should shape deal structure, not follow it. Involving your personal tax advisor alongside your M&A legal team before signing an LOI can help avoid tax costs that cannot be recovered after signing.
3. Designing Deal Terms for Post-Sale Financial Security
The headline valuation in a term sheet can matter less than the cash flow mechanics behind it. Your M&A, tax and wealth advisers should work together to balance deal structure against personal financial security.
- Cash at Close: Carries the lowest structural risk. These proceeds are available for an investment plan matched to your post-exit income and lifestyle needs.
- Rolled Equity: Involves high structural risk. Re-investing in the acquiring company should be evaluated as a concentrated position requiring downside protection and explicit secondary liquidity terms.
- Earn-Outs: Carry high operational risk. Treat earn-out payments as speculative upside rather than core wealth projections due to post-sale integration uncertainties.
- Seller Notes: Involve meaningful credit risk. A seller note is effectively a loan to the buyer, usually subordinated to the senior lender and often unsecured, so negotiate the interest rate, maturity, covenants and any security or guarantees carefully.
4. Post-Transaction Liquidity and Portfolio Architecture
Transitioning overnight from an illiquid, high-growth asset to a liquid capital portfolio requires a disciplined wealth preservation mindset. Managing newly liquid wealth requires planning how portfolio income will replace business cash flow.
- Mitigating Founder Shock: Transitioning from driving business growth to managing investment risk can lead to overly aggressive re-investment. Establishing an asset allocation model early can help keep you focused on long-term wealth preservation.
- Staggered Asset Deployment: Some founders phase their cash into the market over several months to reduce the risk of investing everything at a peak. Historically, investing a lump sum at once has outperformed phasing in about two-thirds of the time, so this is a trade-off between expected return and regret. Either way, keep a liquidity reserve for taxes and the earn-out and escrow periods.
- Liability and Asset Protection: Post-sale visibility can increase your exposure to legal claims. Umbrella liability insurance and, where state law permits, asset protection trusts can help protect new liquidity. New York does not recognize self-settled asset protection trusts, and transfers made once a claim is foreseeable can be unwound.
Maximize Enterprise Value and Personal Net Worth
An exit is a single event, but its financial impact spans generations. By coordinating M&A advisory with wealth management early, you improve the chances that more of the value you have built translates into long-term personal security.
Planning an exit within the next 1 to 3 years? Contact us to discuss how our advisory services may be relevant to your situation. We do not provide legal, tax or accounting advice, and no transaction or investment outcome is guaranteed.
Important disclosures
This material is provided for informational and educational purposes only. It does not constitute investment, legal, tax, accounting or estate-planning advice and should not be relied upon as such. The strategies described involve complex tax and legal rules, may not be suitable for every individual, and should be evaluated with your own tax, legal and financial advisers. Nothing in it is an offer to sell or a solicitation of an offer to buy any security. Receipt of this material does not create an advisory or client relationship. An advisory relationship is established only upon execution of a written agreement.
Information is as of October 11, 2026 and is subject to change without notice. Tax law in particular changes frequently. Figures cited reflect sources believed to be reliable but are not guaranteed. Statements about future events or outcomes are forward-looking and may prove incorrect. There is no guarantee that any strategy will achieve its objective or reduce taxes. Past performance does not guarantee future results. All investing involves risk, including the possible loss of principal, and asset allocation does not ensure a profit or protect against loss.
Calado Capital is a registered investment adviser. Registration does not imply a certain level of skill or training. Calado Capital may transact business only in states where it is registered or is excluded or exempt from registration. Additional information about Calado Capital, including its Form ADV Part 2A brochure, is available at adviserinfo.sec.gov.
Latest Newsletter
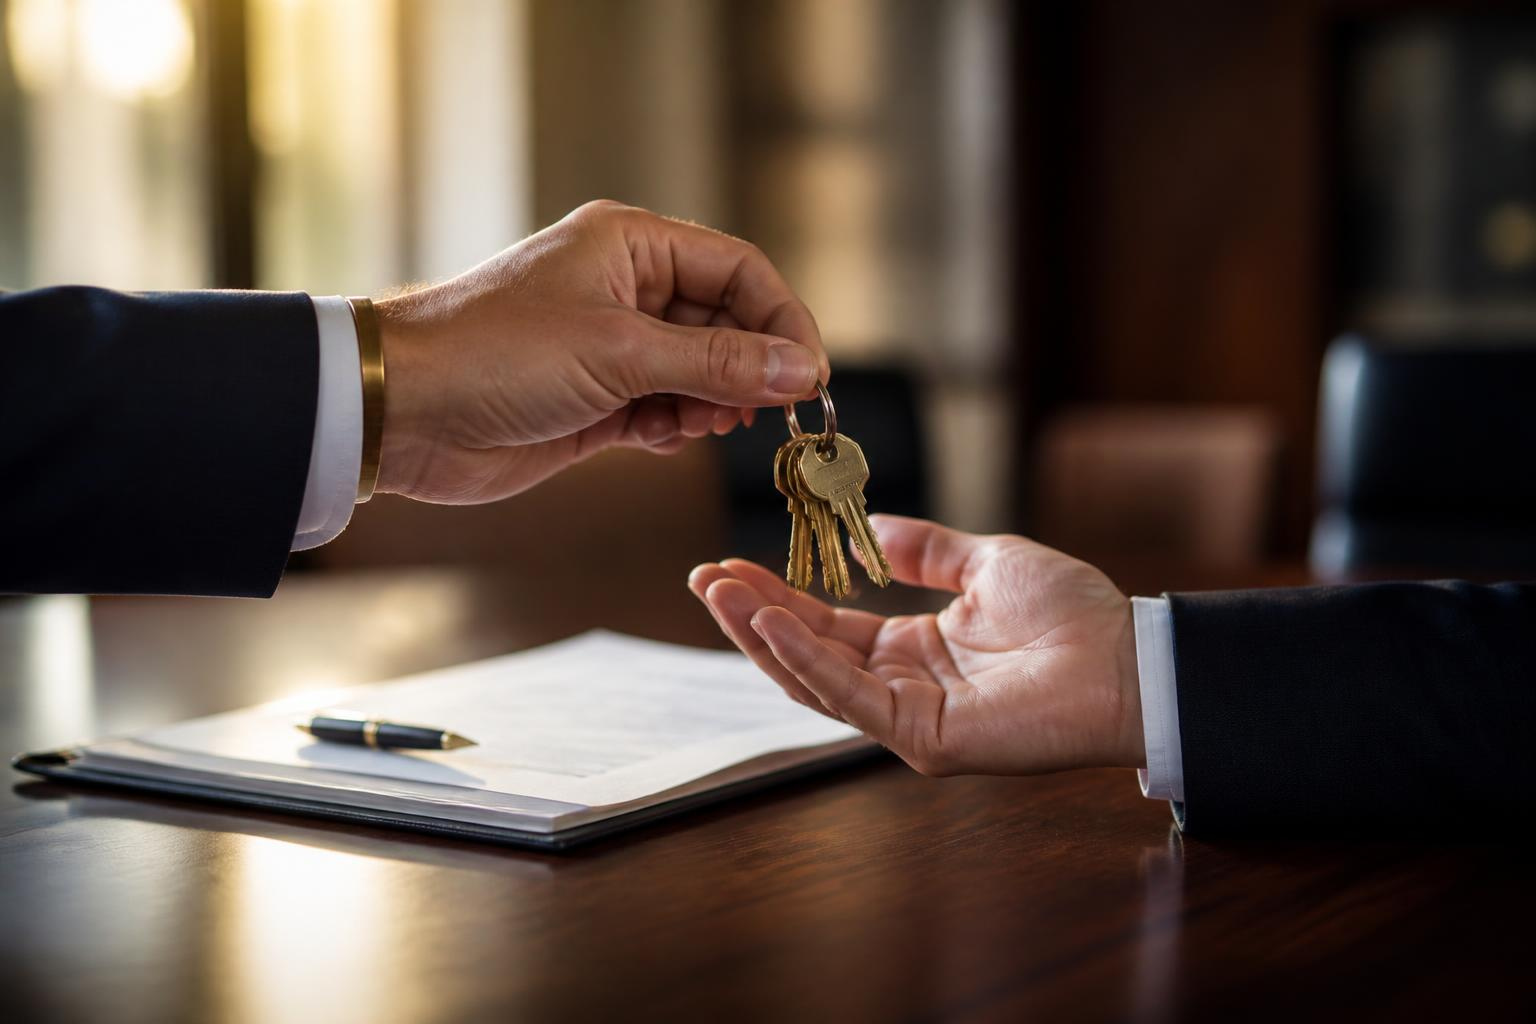
The Entrepreneur’s Exit Roadmap: Integrating M&A Strategy with Personal Wealth Preservation
Claudio Calado2026-10-12T19:45:08+00:00October 21, 2026|
Week in review and ahead (vol.42-26)
Claudio Calado2026-10-19T03:42:07+00:00October 19, 2026|
Week in review and ahead (vol.41-26)
Claudio Calado2026-10-11T02:37:24+00:00October 11, 2026|
